
Egypt Daily News – Egypt News.
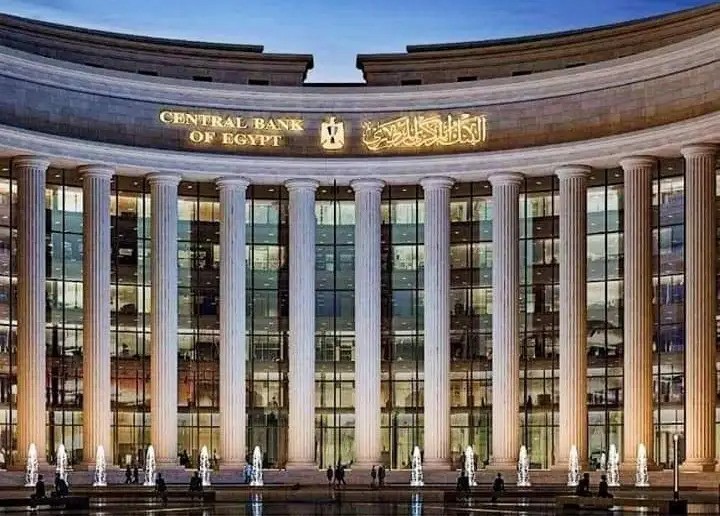
A customer in a village without a bank branch may soon be able to take some routine banking requests to an authorized local agent instead. New rules approved by the Central Bank of Egypt allow banks to use contracted agents to provide selected services on their behalf, including verifying customers’ identities.
The change is designed to extend banking access beyond the branch network, particularly in remote areas where opening or reaching a bank branch can be difficult. Under the framework, customers may be able to open accounts, update their bank details and submit applications for certain services at an agent’s outlet.
For banks, the arrangement offers a way to serve more people through local partners rather than relying only on their own branches. For customers, it could reduce the distance and time involved in completing basic tasks. The central bank has not announced when individual banks will begin using agents or identified which businesses will qualify.
The new rules establish the regulatory framework for that activity. Banks must meet minimum standards and controls when they provide services through contracted agents, and they must obtain central bank approval to conduct agent-banking activities. The agents themselves must also be approved.
Customer identification is among the permitted functions. It is a significant inclusion in the rules because verifying a person’s identity is often required before a bank can open an account or provide financial services. Allowing an approved agent to perform that step could make the process more accessible, but it also places responsibility on banks to ensure their agents follow the required procedures.
The Central Bank of Egypt said the framework is intended to expand access while protecting customers’ rights and keeping their information confidential. Banks will remain responsible for the services provided on their behalf, and the minimum standards are meant to establish consistent controls across agent arrangements.
The decision comes as Egypt seeks to bring more people into the formal financial system. The central bank reported that the country’s financial inclusion rate reached 79% in June 2026, a 229% increase compared with 2016. The measure includes access to active financial accounts, such as bank and postal accounts, mobile wallets and prepaid cards.
That figure indicates substantial progress, but it also leaves room for the authorities to broaden access and encourage people to use financial services. A nearby agent could be particularly useful where the obstacle is not a lack of interest in banking, but the cost or inconvenience of reaching a branch. Whether the new rules make a practical difference will depend on where agents operate, which services they can offer and how clearly customers understand the process.
Agent banking also brings risks that need to be managed. Customers must know whether they are dealing with an authorized representative, what information they are being asked to provide and how their data will be protected. The rules’ approval and oversight requirements are intended to provide safeguards, but implementation by individual banks will be crucial.
The framework builds on a broader series of central-bank initiatives aimed at widening access to financial services. In August, the central bank issued rules allowing remote bank-account opening through electronic customer identification. Other measures have simplified account opening for individuals and micro-businesses, including young people, freelancers and artisans.
Together, the measures point to a broader shift in how customers may interact with banks: some services can be accessed digitally, while others may be delivered through approved local outlets. Agent banking adds a physical point of access in places where a bank branch may not be available, complementing rather than replacing digital channels.
The central bank’s next challenge will be turning the new rules into a functioning network that reaches people currently underserved by banks. That will require banks to choose and supervise suitable agents, make services easy to access and maintain clear protections for customers. The approval creates the regulatory route; the scale and usefulness of the service will depend on how banks put it into practice.
